SPAC Attorney Texas

By Managing Partner Last updated

Acquisition Stars advises buyers and sellers on spac attorney matters across Texas.

Serving 2 markets across Texas.

Request Engagement Assessment
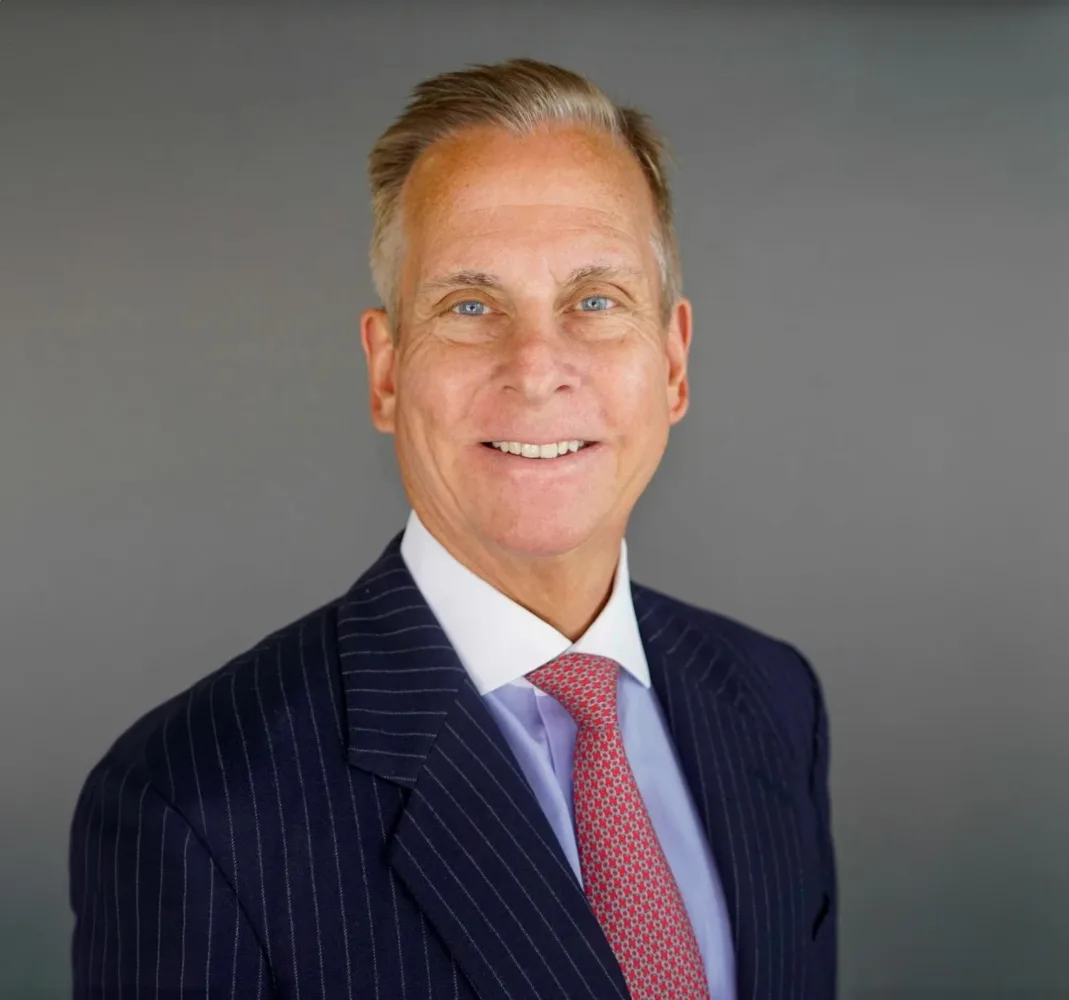
Donald Hateley, Of Counsel for securities law at Acquisition Stars

Donald Hateley

Of Counsel, Securities Law | Acquisition Stars

Donald Hateley serves as Of Counsel to Acquisition Stars for securities law matters. His background includes advising public and private companies on securities transactions, corporate finance, and corporate governance, including public and private equity and debt financings. Admitted to the California bar in 1993, he is a graduate of the University of Southern California Marshall School of Business and Southwestern Law School.

Request Engagement Assessment

Discuss Your Texas Transaction

Share the basics. Alex reviews every inquiry and responds within one business day.

Please do not include confidential information in this form. Submitting this form does not by itself create an attorney-client relationship. Privacy Policy

SPAC Attorney Service Areas in Texas

Acquisition Stars represents clients in each of the following markets. Click any city to learn about spac & business combination law services in that area.

Deal context in Texas

A special purpose acquisition company, or SPAC, is a publicly traded shell company formed to raise capital through an IPO and then combine with a private operating company within a set window, typically around 24 months. For a Texas target in energy, technology, or healthcare, a SPAC merger can move faster than a traditional IPO, since the shell company is already registered and the deal proceeds through a merger agreement and shareholder vote rather than a full IPO roadshow. If the combination is not completed before the deadline, the trust holding investor funds is returned to shareholders and the deal is off.

Most de-SPAC transactions pair the merger with a PIPE, a private investment in public equity, raised to backstop redemptions and fund the combined company's balance sheet after closing. The SEC's SPAC rules adopted in January 2024 tightened disclosure obligations around projections, dilution, and conflicts of interest, and moved underwriter liability standards closer to those of a traditional IPO. For a Texas target, the proxy statement or Form S-4 supporting the shareholder vote now requires the same disclosure discipline as a conventional public offering.

Texas energy, technology, and healthcare companies are frequent SPAC targets because sponsors actively search for operating businesses with real revenue and a credible path to public-company reporting, and Texas produces a steady supply of them. Compared with a traditional sale to a strategic buyer or private equity fund, a SPAC merger trades a single negotiated purchase price for public market valuation, ongoing SEC reporting obligations, and a shareholder base that can redeem shares before closing, which changes both the certainty and the mechanics of getting paid.

Texas Legal Framework for SPAC & Business Combination Law

Non-Compete Laws

Enforceable only if ancillary to an otherwise enforceable agreement. Mandatory reformation.

Tax Considerations

Texas has no corporate income tax and no personal income tax. The state imposes a Franchise (Margin) Tax on entities with total revenue exceeding $2.47 million (2024 threshold), at rates of 0.375% (retail/wholesale) or 0.75% (other). As a community property state, Texas gives each spouse sole management and disposition of the community property that spouse would have owned if single, and leaves the remaining community property to the joint management of both spouses unless they agree otherwise in writing, under Tex. Fam. Code 3.102. The no-income-tax environment significantly affects deal structuring.

Texas Regulatory Notes

  • The Texas Attorney General reviews acquisitions involving nonprofit organizations and charitable trusts. The Texas Department of Insurance reviews insurance company ownership changes. The Public Utility Commission of Texas reviews electric utility acquisitions. The Railroad Commission regulates oil and gas-related transactions.
  • Texas raised the Franchise Tax no-tax-due threshold to $2.47 million in total revenue for 2024, exempting more small businesses. The state also expanded the appraisal dispute process, which can affect real property valuations in acquisitions.

SPAC Attorney in Texas: Frequently Asked Questions

What is a SPAC, and how does SPAC law apply to a Texas company?

A SPAC is a shell company that raises capital through an IPO to acquire or merge with a private operating business, and SPAC law covers the securities, disclosure, and governance rules that apply from formation through the de-SPAC merger. For a Texas target, this means SEC registration and disclosure requirements, a shareholder vote on the business combination, and coordination with Texas entity law for the merger itself.

How much does SPAC legal representation cost in Texas?

SPAC and de-SPAC fees scale with the complexity of the transaction, not a flat rate. A straightforward business combination costs less to document than one involving multiple PIPE investors, contested redemption terms, or extended SEC review. Acquisition Stars typically stages SPAC engagements so a sponsor or target understands the scope of work, on the M&A side and with securities counsel, before committing to full transaction drafting. More complex combinations carry larger fees because they require more attorney time across the merger workstream and coordination with securities counsel.

How do the SEC's 2024 SPAC rules affect a Texas de-SPAC?

The SEC adopted new SPAC-specific rules in January 2024 that tightened disclosure requirements around financial projections, dilution, sponsor compensation, and conflicts of interest, and moved underwriter liability standards closer to those of a traditional IPO. For a Texas target, the practical effect is a proxy statement or Form S-4 requiring the same disclosure discipline as a conventional public offering. Sponsors working under an older SPAC playbook need to update their documentation approach accordingly.

What is PIPE financing, and why does a Texas SPAC target need it?

A PIPE, or private investment in public equity, is capital raised from institutional investors alongside a de-SPAC merger, typically used to backstop shareholder redemptions and fund the combined company after closing. Texas targets in capital-intensive sectors like energy often need a PIPE because public shareholders can redeem shares for cash before the merger closes, which can leave the trust holding less than expected.

Does the Texas Business Court handle SPAC or de-SPAC disputes?

The Texas Business Court, launched in 2024, handles complex commercial disputes above a defined amount-in-controversy threshold, including business governance and securities-adjacent matters that can arise from a contested SPAC transaction. A sponsor or target facing a dispute over merger terms, redemption calculations, or sponsor compensation may find those matters routed to the Business Court rather than a general civil docket. This page focuses on the transactional side of a SPAC deal; disputes are handled separately.

Request Engagement Assessment

Alex reviews each inquiry within one business day.

Request Engagement Assessment

How We Work

1

Sponsor and Target Diligence

We coordinate due diligence on both sides of a Texas SPAC transaction, from the sponsor's trust account and promote structure to the target's financial and operational readiness for public company reporting.

2

Merger Agreement Negotiation

We negotiate the business combination agreement's redemption mechanics, purchase price adjustments, and closing conditions, working against the SPAC's fixed deadline so momentum does not stall while terms are finalized.

3

Proxy Statement and S-4 Coordination

We work with securities counsel on the proxy statement or Form S-4 disclosure required for the shareholder vote, and coordinate the M&A timeline so projections, dilution figures, and sponsor conflict disclosures align with the SEC's 2024 SPAC-specific rules.

4

PIPE Documentation and Closing

We coordinate the PIPE closing conditions alongside the merger agreement, and work with securities counsel on documenting PIPE investor commitments, so redemption risk is addressed with committed backstop financing before the shareholder vote.

Ready to Discuss Your Texas Deal?

Donald Hateley serves as Of Counsel to Acquisition Stars and handles the securities law work. Alex Lubyansky leads the M&A work, with an associate supporting the engagement.

M&A counsel since 2013. Nationwide practice. LOI through closing.

Request Engagement Assessment

We review every transaction inquiry within one business day.

Please do not include confidential information in this form. Submitting this form does not by itself create an attorney-client relationship. Privacy Policy