By Alex Lubyansky Managing Partner Last updated
SPAC & Business Combination Law representation for buyers, sellers, and operators nationwide.
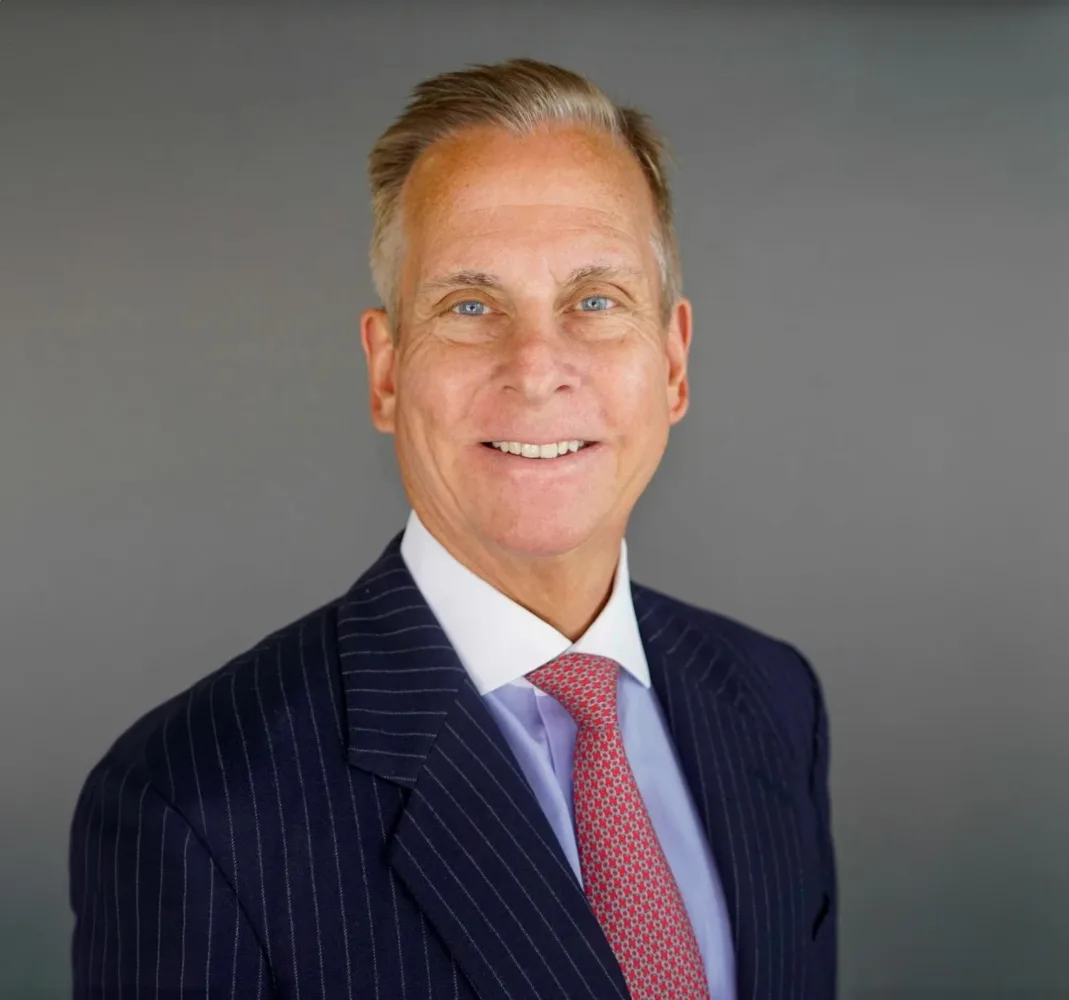
Donald Hateley serves as Of Counsel to Acquisition Stars on securities law matters.
Request Engagement AssessmentShare your transaction stage, the help you need and any relevant deadline.
Your transaction details are under review. If there is alignment, we will be in touch.
Meanwhile, feel free to call us directly at (248) 266-2790
Of Counsel, Securities Law | Acquisition Stars
Donald Hateley serves as Of Counsel to Acquisition Stars for securities law matters. His background includes advising public and private companies on securities transactions, corporate finance, and corporate governance, including public and private equity and debt financings. Admitted to the California bar in 1993, he is a graduate of the University of Southern California Marshall School of Business and Southwestern Law School.
Request Engagement AssessmentA SPAC attorney, also called a SPAC lawyer, represents sponsors, target companies, and PIPE investors through SPAC formation, the IPO, and the de-SPAC business combination. The work covers sponsor equity and promote structures, proxy statement and shareholder approval requirements, PIPE financing, and post-combination governance. Acquisition Stars helps clients with the M&A side of the de-SPAC business combination and works with securities counsel on the SPAC formation, IPO, proxy statement, and compliance work.
A SPAC transaction runs on a fixed deadline: the sponsor generally has a limited window set in the SPAC's governing documents, often around 24 months, to complete a business combination before the trust account must be returned to shareholders. That clock shapes nearly every negotiating decision, from the target search to the PIPE terms to the shareholder vote. A SPAC lawyer who has handled the proxy and de-SPAC mechanics before can help the sponsor and the target keep the transaction moving inside that window, since a stalled negotiation is not just a cost, it can end the deal entirely if the deadline passes.
A special purpose acquisition company, or SPAC, is a listed shell company with no operating business. It raises money from public investors and holds that money in a trust account while it looks for a company to combine with. The target is an operating business that wants to become part of the listed company. The parties sign a merger agreement, and the SPAC's shareholders often vote on the combination. In connection with the combination, shareholders usually have the right to redeem their shares for a pro rata portion of the trust account, instead of staying in the combined company. If the combination closes, the target's business becomes the listed company's business, and the funds left in the trust help finance it. M&A counsel for the target reviews how the structure works and who must approve each step.
A target weighing a SPAC merger against a traditional IPO is choosing between two routes to a public listing, and the routes work differently. In an IPO, the company sells its own shares to investors through underwriters. In a SPAC merger, the company negotiates a merger agreement with one counterparty, the SPAC, and its owners receive shares or other consideration under that agreement. That changes who sets the terms. A SPAC deal has a negotiated price, a counterparty with its own sponsor and deadline, and an outcome that depends on shareholder votes and redemptions. An IPO is priced through the underwriting process. Neither route is the better choice for every company. The target should compare control, certainty of the outcome, who bears which costs, and what its owners may sell or must hold after closing.
Diligence in a SPAC merger runs in both directions. The SPAC reviews the target's business, contracts, financial records, ownership and liabilities, much as any buyer would. The target should also review the SPAC. That includes its governing documents, the terms of its public offering, the sponsor's agreements, and the amount and status of the trust account. Sponsor economics deserve particular attention. The sponsor often holds founder shares or similar interests that may have value mainly if a combination closes, so its incentives can differ from those of public shareholders and the target. These conflicts of interest are a diligence topic and a disclosure topic. The parties address them mainly in the sponsor agreements and in the documents sent to shareholders. M&A counsel helps the target ask who benefits from each term.
Several terms often decide how a SPAC merger is funded and priced. A PIPE is a private investment in the combined company, usually committed at signing and funded at closing. It brings in cash that does not depend on the redemption choices of the SPAC's shareholders. A minimum cash condition is a closing condition. It lets a party decline to close unless the cash available at closing, after redemptions, meets a level set in the merger agreement. Redemptions matter because each redeemed share takes money out of the trust that would otherwise be available at closing. An earnout gives target owners or others additional shares if the combined company meets stated goals after closing. The merger agreement defines each goal, the measurement period and the result if a goal is missed. The target should model these terms together, since heavy redemptions can decide whether the cash condition is met.
A SPAC has a deadline in its governing documents to complete a business combination. If it does not finish in time, the documents set what happens next, which commonly includes returning the trust funds to public shareholders. A deadline that is close can limit the time for diligence and negotiation. A SPAC may seek an extension, but only through the steps those documents require, such as a shareholder vote and a chance to redeem. Those steps can change how much cash remains in the trust. The deal also involves directors and officers insurance. D&O coverage is a negotiated item, and its terms, such as who is covered and for what period, are set in the deal documents and the policy. Securities counsel addresses the securities law questions that come with these steps.
"The hardest part of any SPAC and business combination engagement is not the documents. It is reading the relationship across the table early enough to structure around it. By the time the purchase agreement is on the table, the main terms are often already set in the letter of intent."
Buy-side and sell-side representation Admitted in Michigan, practicing nationwide
Use these before you call any firm, including ours.
Ask any firm you consider this question before you sign an engagement letter.
Volume indicates current, active deal experience, not just credentials from years ago.
Make sure the attorney has handled transactions similar in size and structure to yours.
Your attorney should work with your other advisors, not in a silo.
Reps, warranties, and indemnification claims surface months after closing. Ask whether the firm handles post-closing litigation or refers it out.
Ask how the engagement is scoped, what is included, and what factors drive cost increases.
Browse service areas by state. Each state page lists all cities and suburbs we serve in that state, plus the state-specific legal framework that affects these transactions there.
Acquisition Stars handles M&A transactions nationwide and works with securities counsel on securities matters.
A SPAC lawyer represents the sponsor from formation through the IPO and into the search for a target, handling the sponsor equity and promote structure, the registration statement, and the trust account mechanics that hold investor funds until a business combination closes. Once a target is identified, the same SPAC law firm typically leads the de-SPAC negotiation, the proxy statement, and the shareholder approval process through closing.
A de-SPAC transaction combines a merger agreement with public company disclosure obligations, since the SPAC is already publicly traded and the target is effectively going public through the combination. That means proxy statement preparation, shareholder approval, and PIPE financing terms all move in parallel with the merger negotiation itself, on a timeline set partly by the SPAC's remaining deadline to complete a combination. A SPAC lawyer coordinates these workstreams together rather than treating the merger and the public company disclosure as separate problems.
Most SPACs have a deadline set in their governing documents, often around 24 months from the IPO (the SEC describes the period as typically two years), to complete a business combination or return the trust account funds to public shareholders. If that deadline passes without a completed deal, the SPAC generally dissolves and the trust is distributed, which is why sponsors and target companies both work under real time pressure once a letter of intent is signed. A SPAC law firm familiar with these mechanics can help the sponsor manage that deadline risk throughout the search and negotiation.
Donald Hateley serves as Of Counsel to Acquisition Stars on securities law matters.
The firm represents SPAC sponsors forming new SPACs, private companies considering de-SPAC transactions, institutional investors in PIPE financings, along with other parties involved in mid-market and lower-middle-market transactions. Engagements range from single-buyer acquisitions to multi-party recapitalizations.
Yes. While the firm office is in Novi, Michigan, the firm represents clients nationwide on M&A transactions. Engagements can involve out-of-state buyers, sellers, or target companies. The firm regularly admits pro hac vice in other states when matters require it.
Pricing varies with deal size, complexity, and timeline, so Acquisition Stars does not publish a fee schedule. After a brief initial conversation about the deal specifics, the firm provides a written engagement scope.
Donald Hateley serves as Of Counsel to Acquisition Stars on securities law matters.
Nationwide practice. LOI through closing.
We review every transaction inquiry within one business day.
Your transaction details are under review. If there is alignment, we will be in touch.
Meanwhile, feel free to call us directly at (248) 266-2790
Before you go
Talk through your transaction with Alex Lubyansky at no cost. Submit your transaction details and the team will confirm next steps.
Request Your Free ConsultationOr call (248) 266-2790